
Sources reviewed September 16, 2026 · Editorial Policy
A money market account and a high-yield savings account can both help your cash earn interest. Both are deposit accounts when offered by a bank or credit union. Both may also have variable rates, fees, minimum-balance rules and federal insurance.
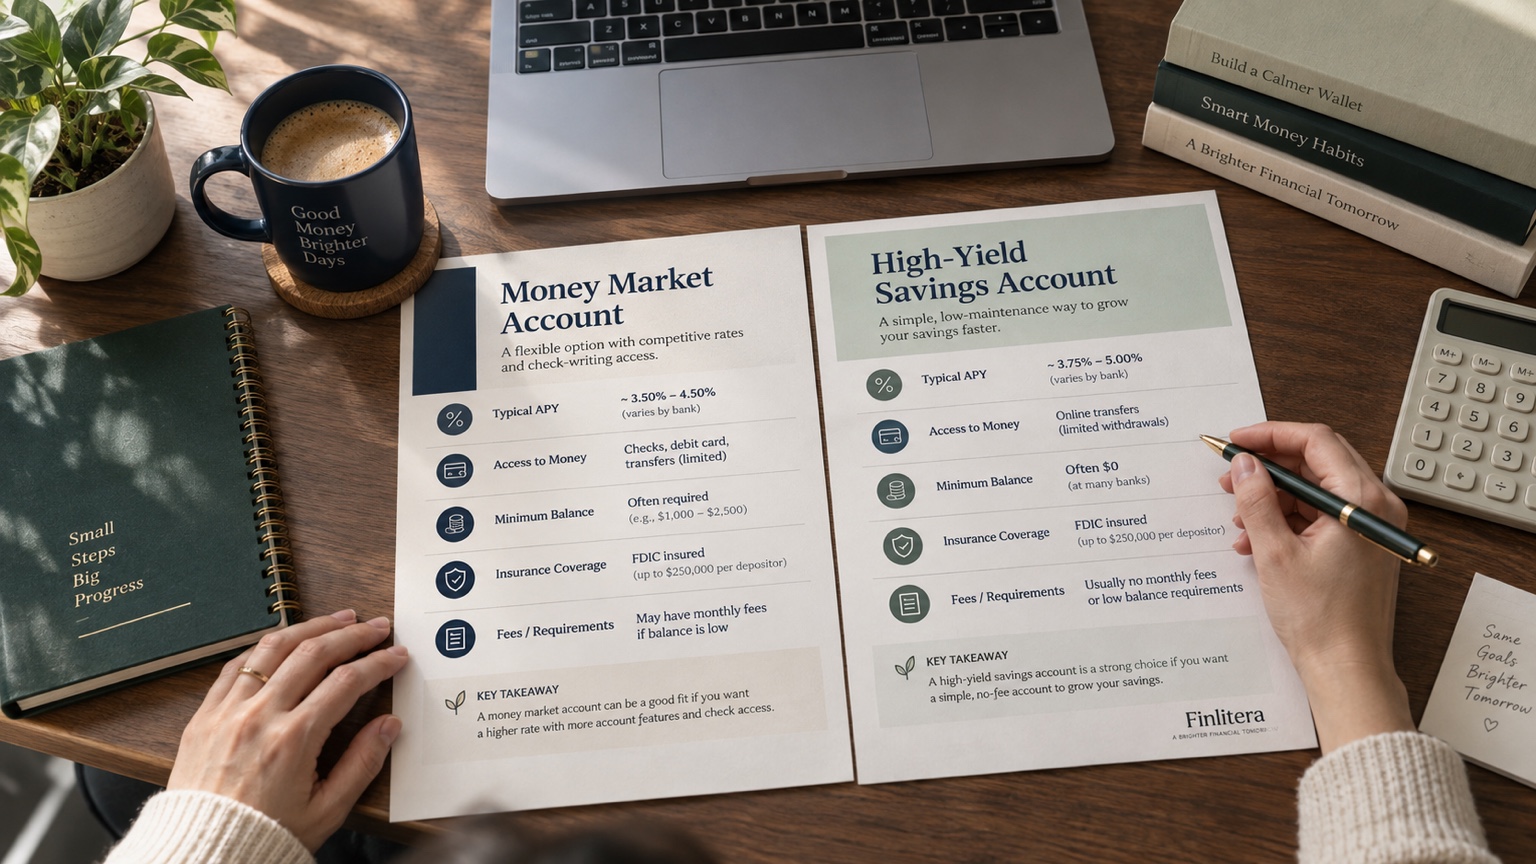
The main difference is access. A money market account may include checks, a debit card or ATM access. A high-yield savings account often expects you to move money electronically to another account before spending it.
Choose the account whose access rules, fees and balance requirements fit your goal—not the account with the most impressive label.
This guide compares the two account types without using temporary rate offers. It also explains the insurance rules and the important difference between a money market account and a money market fund.
Quick answer
A high-yield savings account may be the simpler choice when you want to build an emergency fund, avoid minimum-balance requirements and make occasional electronic transfers.
A money market account may be useful when you want savings-account interest plus limited access by check, debit card or ATM. Those features depend on the institution.
Neither account is always better. Compare the live annual percentage yield, or APY, on the same day. Then compare fees, minimums, access methods, transaction rules and federal insurance.
What is a money market account?
A money market account is a deposit account offered by a bank or credit union. It earns interest and may combine features of savings and checking accounts.
Depending on the account, you may receive:
- A debit or ATM card
- Limited check-writing ability
- Electronic transfers
- Online bill payments
- A tiered APY based on your balance
These features are not guaranteed. One institution may offer a debit card but no checks. Another may require a larger balance to earn its highest APY or avoid a monthly fee.
The Consumer Financial Protection Bureau says money market accounts may limit transactions made by check, debit card or electronic transfer. Federal Regulation D no longer sets the old six-per-month limit on convenient transfers from savings deposits. However, an institution can still set its own limits or fees under the account agreement.
Read the current disclosure instead of assuming every money market account works the same way.
What is a high-yield savings account?
A high-yield savings account is a savings account that pays an APY that is competitive with many other savings accounts. “High yield” is a marketing label. There is no permanent APY that makes an account high yield.
Many high-yield savings accounts are offered online. They may have no debit card or check-writing feature. To spend the money, you may need to transfer it to a checking account first.
That extra step can be useful. It may keep savings separate from daily spending. It can also be inconvenient if a transfer takes longer than expected.
For a complete explanation, read What Is a High-Yield Savings Account?
Money market account vs. high-yield savings account
The exact terms matter more than the account name.
| Feature | Money market account | High-yield savings account |
|---|---|---|
| Account type | Deposit account | Deposit account |
| APY | Usually variable; may use balance tiers | Usually variable; may have conditions |
| Check access | Sometimes included | Usually not included |
| Debit or ATM card | Sometimes included | May be unavailable or limited |
| Electronic transfers | Usually available | Usually available |
| Minimum balance | May be higher | Often lower, but varies |
| Monthly fee | Possible | Possible |
| Transaction limits | Institution rules may apply | Institution rules may apply |
| Federal insurance | Available at an eligible insured institution within coverage rules | Available at an eligible insured institution within coverage rules |
| Best fit | Savings that may need limited direct access | Savings kept separate from routine spending |
This table describes common patterns, not promises. Check the disclosure for the specific account you are considering.
Which account usually pays more interest?
There is no reliable rule that one account type always pays more.
A high-yield savings account may offer a stronger APY than a money market account at one institution. A money market account may offer the better APY somewhere else. The order can change as institutions adjust their rates.
Use APY when comparing accounts. APY reflects the interest rate and compounding over a 365-day period. Compare APY against APY on the same date.
Then check whether the advertised APY:
- Applies to your full balance
- Requires a minimum balance
- Is limited to a balance range
- Requires direct deposit or another activity
- Is promotional or variable
- Can be reduced by monthly fees
An account with a slightly lower APY may leave you with more money if it has no monthly fee and no hard-to-meet requirement.
A simple comparison example
Suppose you have $8,000 for an emergency fund. You are comparing two fictional accounts:
| Example account | Example APY | Monthly fee | Minimum to avoid fee | Access |
|---|---|---|---|---|
| Money market account | 3.80% | $10 | $5,000 | Debit card and checks |
| High-yield savings | 3.90% | $0 | $0 | Electronic transfer |
If each example APY stayed unchanged for one year and the balance stayed at $8,000:
- The money market account would earn about $304 before any fee.
- The high-yield savings account would earn about $312.
- The difference would be about $8.
If you keep at least $5,000 in the money market account, you avoid its example fee. If your balance falls below that level for several months, the fees could cost more than the small APY difference.
These are educational estimates, not current offers or guaranteed results. Actual interest depends on the account’s APY, compounding method, balance, fees, deposits, withdrawals and rate changes.
The example shows why the full account terms matter. A tiny APY advantage may be less important than reliable access or a fee you can avoid.
How access differs
Access is often the clearest difference.
Money market account access
A money market account may let you write checks or use a debit card. This can make it easier to pay a large planned expense directly from savings.
That convenience can also make the account easier to spend from. It may be a poor fit if you want a strong barrier between savings and everyday purchases.
High-yield savings access
A high-yield savings account may require an electronic transfer to checking. Some accounts offer ATM access, but others do not.
Before using one for emergencies, test the transfer process. Learn whether transfers are instant, same-day or likely to take several business days. Check for holds on new deposits.
The safest access method is the one you understand and can use when needed.
Are both accounts federally insured?
They can be, but the account must be held at an eligible insured institution.
At an FDIC-insured bank, money market deposit accounts and savings accounts are deposit products. The standard coverage amount is generally $250,000 per depositor, per insured bank, for each account ownership category.
At a federally insured credit union, the National Credit Union Share Insurance Fund provides similar coverage. Individual accounts are generally insured up to $250,000, subject to ownership rules.
Insurance applies to the total eligible deposits you hold in the same ownership category at the same institution. Opening several accounts at one bank does not automatically give each account a separate $250,000 limit.
Verify the institution and coverage:
- Find the legal name of the bank or credit union holding your money.
- Confirm the bank through FDIC BankFind or the credit union through the NCUA Credit Union Locator.
- Add your eligible deposits at that institution by ownership category.
- Use the FDIC or NCUA insurance estimator when your balances may approach a limit.
Do not rely only on an app’s name, logo or statement that funds are “held with partner banks.” Read the program terms and identify the insured institution.
Money market account is not the same as a money market fund
The similar names cause confusion.
A money market account, sometimes called a money market deposit account, is a deposit account offered by a bank or credit union. It may qualify for FDIC or NCUA insurance within the rules.
A money market fund is a mutual fund offered through a brokerage or fund company. It holds short-term securities. It is an investment, not a bank deposit, and it is not insured by the FDIC or NCUA.
Brokerage protections and investment risks are different from deposit insurance. If a screen says only “money market,” confirm whether it means a deposit account or a mutual fund before moving cash.
Fees and requirements to check
Read the account disclosure and fee schedule. Look for:
- A minimum opening deposit
- A minimum balance to earn interest
- A minimum balance to receive the advertised APY
- A monthly maintenance fee
- Transaction or excess-withdrawal fees under the institution’s policy
- ATM fees
- Out-of-network ATM charges
- Check-order fees
- Stop-payment fees
- Wire-transfer fees
- Requirements tied to another account
Federal Truth in Savings rules require covered institutions to disclose key terms such as APY, interest rates, balance requirements, fees and applicable transaction limitations.
Save a copy of the disclosure when you open the account. Terms can change, and the saved document helps you compare the old and new rules.
Which is better for an emergency fund?
Either account can work if it is properly insured, has low fees and gives you access soon enough.
A high-yield savings account may be easier for many beginners because it often has fewer spending features. The separation can reduce impulse spending.
A money market account may be useful if direct check, debit card or ATM access would help during an emergency. Make sure the account’s minimum-balance and transaction rules do not create a problem when you withdraw money.
You can also divide your emergency fund. Keep a smaller amount in an account with immediate access and the rest in an insured account with a competitive APY. The right split depends on your bills, transfer times and comfort level.
Start with Emergency Funds: How Much Do You Really Need? and test your buffer with How Long Would Your Emergency Fund Last?.
If you’re deciding when to keep building cash versus start investing for longer-term goals, read Emergency Fund vs. Investing: Which Should Come First?
When a CD may be a better fit
A certificate of deposit, or CD, may fit money you will not need until a known date. A standard CD usually has a set term and may charge an early withdrawal penalty.
A money market or high-yield savings account usually offers more flexible access, but its rate can change. A CD may offer a stated rate for its term, but it reduces flexibility.
Compare the goal date and access need before chasing yield. Read What Is a Certificate of Deposit? for the full comparison points.
How to choose between the two accounts
Use this process.
1. Name the job for the money
Is it emergency savings, a tax payment, a home repair or another short-term goal? Write down when you may need the money.
2. Decide how you need to access it
Do you need checks, a debit card or ATM access? Or is an electronic transfer enough?
3. Compare APYs on the same date
Rates can change. Record the date and confirm the APY directly with the institution.
4. Test the balance rules
Check whether your normal balance will earn the advertised APY and avoid all monthly fees.
5. Review transaction rules
The old federal six-transfer limit is gone, but an institution may still use its own limits or fees. Read the current agreement.
6. Verify federal insurance
Confirm the legal institution and calculate coverage across your deposits at that institution.
7. Test access with a small amount
Send a small deposit, then test a withdrawal or transfer. Learn the process before moving the full balance.
Common mistakes to avoid
Choosing by account name
“Money market” and “high yield” do not guarantee a strong APY, low fees or easy access.
Comparing rates from different dates
Variable rates can change. Compare live APYs on the same day.
Ignoring the minimum balance
A monthly fee or lower balance tier can erase a small yield advantage.
Confusing an account with a fund
A money market deposit account and a money market mutual fund have different risks and protections.
Assuming unlimited access
Federal rules changed, but the institution may still set transaction limits or fees.
Assuming each account has its own insurance limit
Coverage is based on the depositor, insured institution and ownership category—not simply the number of accounts.
Quick decision checklist
Before opening either account, confirm:
- The legal bank or credit union holding the deposit
- FDIC or NCUA insurance status
- Your coverage across all deposits at that institution
- The current APY and whether it can change
- Any balance needed to earn the advertised APY
- Monthly and transaction fees
- Check, debit card, ATM and transfer access
- Transfer timing and deposit holds
- The institution’s withdrawal or transaction policy
- Whether the account is a deposit account rather than a mutual fund
Frequently asked questions
Is a money market account safer than a high-yield savings account?
Not automatically. Both can have federal deposit or share insurance when held at an eligible insured institution and within the applicable coverage rules. Verify the institution and ownership category.
Can a money market account have a debit card?
Yes, some do. Others do not. Check the account’s access methods and transaction rules before opening it.
Can a high-yield savings account have an ATM card?
Some do, but many rely on transfers to a linked checking account. The name does not guarantee a specific access method.
Do money market accounts have fixed rates?
Usually not. Many have variable rates that the institution can change. Read the disclosure to confirm how the rate works.
Can I lose money in either account?
The balance does not rise and fall with the stock market. Eligible deposits within federal insurance rules are protected if the insured institution fails. Fees can reduce your balance, and inflation can reduce buying power.
Is a money market account good for daily spending?
Usually, it is better for savings with occasional access than for daily transactions. A checking account is designed for frequent payments.
The bottom line
A money market account and a high-yield savings account can both hold short-term savings and earn interest. The better choice depends on access, fees, minimum balances and the live APY—not the product name.
Choose a money market account when its check, debit card or ATM features are useful and its balance rules fit your savings. Choose a high-yield savings account when simple electronic access and separation from daily spending fit your goal.
In either case, verify federal insurance, read the current disclosure and test access before moving a large balance.
This article provides general financial education. It is not individualized financial, investment, tax or legal advice.
Official Sources
- Consumer Financial Protection Bureau — What is a money market account?
- Consumer Financial Protection Bureau — Regulation DD, § 1030.2 Definitions
- Consumer Financial Protection Bureau — Regulation DD, § 1030.4 Account disclosures
- Federal Reserve — Savings Deposits Frequently Asked Questions
- Federal Deposit Insurance Corporation — Electronic Deposit Insurance Estimator
- National Credit Union Administration — Share Insurance Coverage