
Sources reviewed September 5, 2026 · Editorial Policy
A Roth IRA and a traditional IRA can both help you invest for retirement, but they place the main tax benefit at different times.
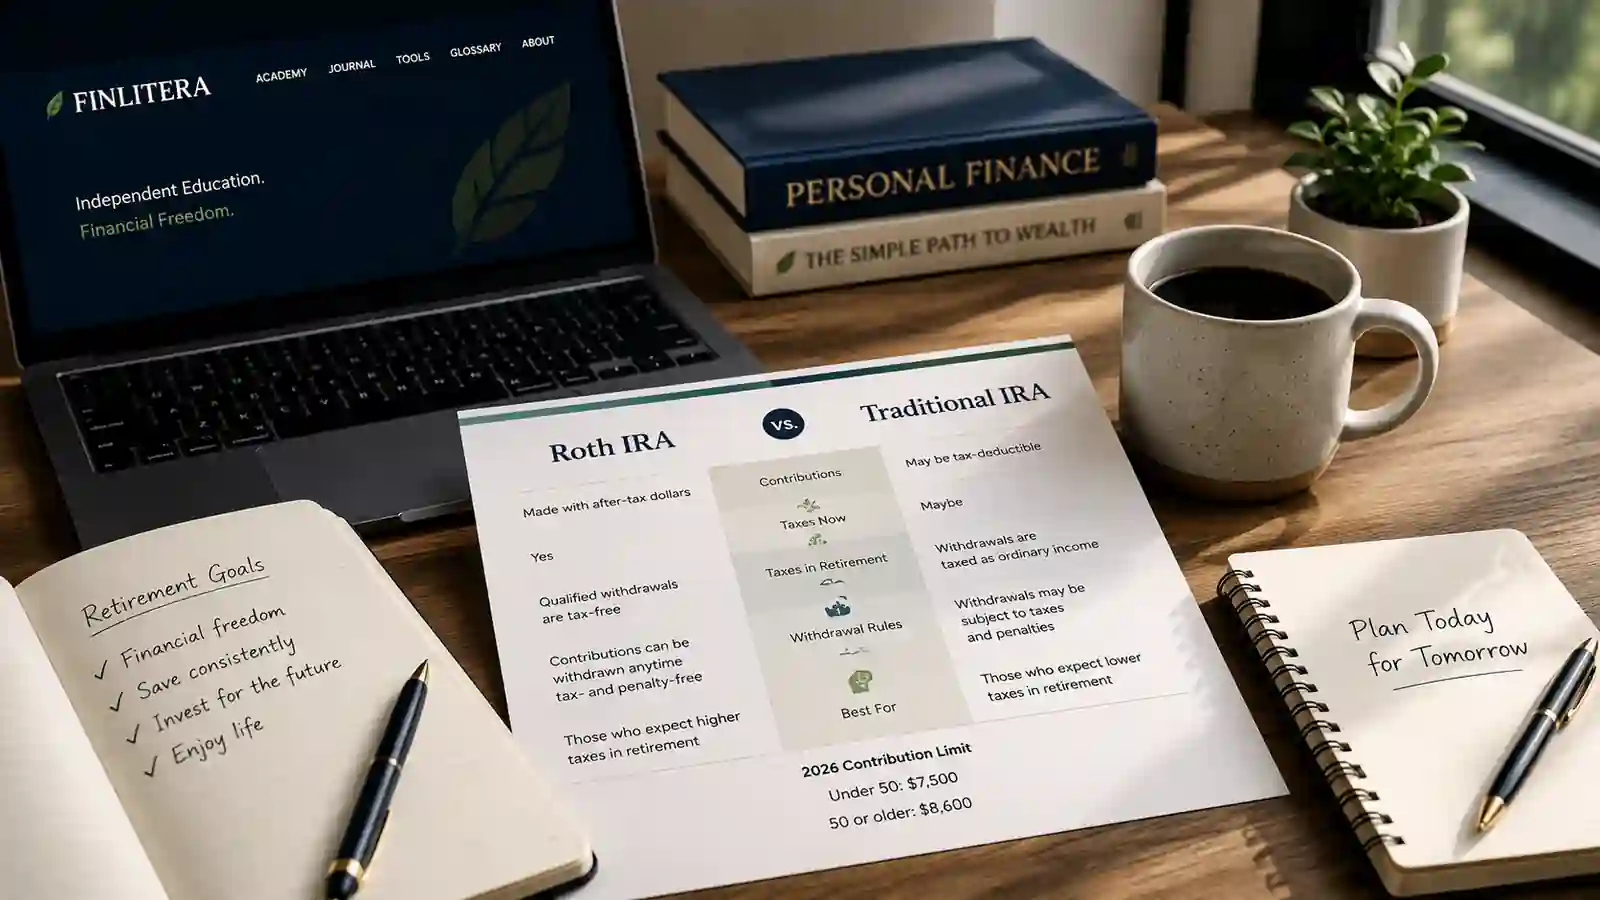
A traditional IRA can give an eligible saver a tax deduction now. Growth is tax-deferred, and most withdrawals are taxable later. Roth contributions use after-tax money. Qualified Roth withdrawals are tax-free.
Neither account is automatically better for everyone. The more useful question is whether a tax break is likely to be more valuable to you now or later—and whether income limits allow the contribution or deduction you want.
The core choice is timing: a traditional IRA may provide a tax benefit now, while a Roth IRA can provide tax-free qualified withdrawals later.
Compare side by side
Review Roth vs. Traditional IRA basics
Use the learning comparison to reinforce the tax-timing and eligibility differences before checking current IRS rules.
Educational tool. Results depend on the assumptions entered and are not personalized financial advice.
Roth IRA vs. traditional IRA at a glance
| Roth IRA | Traditional IRA | |
|---|---|---|
| Contributions | After-tax; not deductible | May be deductible, depending on income and workplace-plan coverage |
| Investment growth | Tax-free when withdrawn in a qualified distribution | Tax-deferred until withdrawal |
| Retirement withdrawals | Qualified withdrawals are tax-free | Deductible contributions and earnings are generally taxed as ordinary income |
| Direct contribution income limit | Yes | No income limit to contribute if you have eligible compensation, but the deduction may be limited |
| Required minimum distributions for original owner | None during the owner’s lifetime | Yes, generally beginning at the applicable RMD age |
| Access before retirement | Regular contributions come out before earnings under Roth ordering rules; tax treatment depends on what is withdrawn | Taxable amounts withdrawn before age 59½ generally face income tax and a 10% additional tax unless an exception applies |
| Often considered by | People who expect a higher future tax rate or value tax-free retirement withdrawals | People who qualify for a deduction and value reducing taxable income now |
This is a general comparison. Conversions, inherited IRAs, state taxes, and nondeductible contributions follow extra rules.
What is a Roth IRA?
You fund a Roth IRA with after-tax dollars. The contribution is not deductible. If a withdrawal is qualified, you owe no federal income tax on the contribution or its growth.
A Roth withdrawal is generally qualified after the five-year rule is met and one approved condition applies. The most common condition is reaching age 59½. Disability, death, or a limited first-home withdrawal may also qualify.
The original Roth IRA owner does not have to take lifetime required minimum distributions. That gives the owner more control over when to use the money.
Income can limit a direct Roth IRA contribution. The permitted amount falls within the annual phase-out range and reaches zero above it.
What is a traditional IRA?
A traditional IRA lets investments grow without annual federal tax inside the account. Tax is usually due when money comes out.
The contribution may be deductible. The answer depends on income, filing status, and workplace-plan coverage for you or your spouse. If neither spouse has such a plan, the usual deduction phase-outs generally do not apply.
You may contribute even when the amount is not deductible. That creates basis, which you normally track on IRS Form 8606. Good records help prevent the same dollars from being taxed twice.
Withdrawals of deductible contributions and earnings are generally taxed as ordinary income. The original owner must also take required minimum distributions at the age set by current law.
The 2026 IRA contribution limit
For 2026, the combined contribution limit for all of your traditional and Roth IRAs is:
- $7,500 if you are under age 50 at the end of 2026
- $8,600 if you are age 50 or older, including the $1,100 catch-up contribution
- Your taxable compensation for the year, if that amount is lower
The limit is shared across your IRAs. It is not $7,500 for each account.
Example: a 35-year-old contributes $4,500 to a Roth IRA for 2026. That leaves up to $3,000 for a traditional IRA, provided the person has enough eligible compensation and otherwise qualifies.
Most IRA contributions are due by the federal tax filing deadline for that year, without extensions. If you contribute from January through the deadline, tell the provider which tax year to use.
2026 Roth IRA income limits
Your ability to make a direct Roth IRA contribution depends on modified adjusted gross income and filing status. For 2026, the IRS phase-out ranges are:
| Filing status | Full contribution below | Phase-out range | No direct contribution at or above |
|---|---|---|---|
| Single or head of household | $153,000 | $153,000–$168,000 | $168,000 |
| Married filing jointly | $242,000 | $242,000–$252,000 | $252,000 |
| Married filing separately and lived with spouse during the year | $0 | $0–$10,000 | $10,000 |
Your Roth limit falls within the phase-out range. At the top of the range, you generally cannot make a direct Roth contribution.
Modified AGI is not always the same as salary. Excess Roth contributions can face a 6% tax for each year they remain. Recheck your limit if income changes or is near the cutoff.
A “backdoor Roth IRA” usually starts with a nondeductible traditional IRA contribution and then a Roth conversion. Existing pretax IRA balances can make part of the conversion taxable under the pro-rata rule. Review Form 8606 and consider tax advice before acting.
2026 traditional IRA deduction limits
Eligible compensation can allow a traditional IRA contribution at any income. Higher income may still reduce or remove the deduction.
If the person making the contribution is covered by a workplace retirement plan, the 2026 deduction phase-out ranges are:
| Filing status | 2026 modified AGI phase-out range |
|---|---|
| Single or head of household | $81,000–$91,000 |
| Married filing jointly, contributor covered at work | $129,000–$149,000 |
| Married filing separately, contributor covered at work | $0–$10,000 |
If only your spouse has a workplace plan and you file jointly, the 2026 deduction phase-out is $242,000–$252,000.
This distinction matters: being allowed to contribute to a traditional IRA is not the same as being allowed to deduct the contribution.
The tax-break-today vs. tax-break-later decision
Compare your tax rate now with the rate you expect on retirement withdrawals.
- If your current tax rate is relatively low and you expect a higher rate later, paying tax now through a Roth IRA may be attractive.
- If your current rate is relatively high, you qualify for a traditional IRA deduction, and you expect a lower rate later, the current deduction may be more valuable.
- If the future is uncertain, holding both tax treatments over time can reduce dependence on one future tax outcome.
This is only an estimate. Future tax law, income, state, filing status, Social Security, and other retirement income can change the result.
A simplified example
Example: two eligible investors each contribute $5,000. One deducts a traditional IRA contribution in the 22% federal bracket. The other puts $5,000 in a Roth IRA.
- The deductible traditional contribution could reduce current federal income tax by approximately $1,100: $5,000 × 22%.
- The Roth contribution does not create a current deduction.
- If both accounts later reach the same balance, qualified Roth withdrawals would be federally tax-free, while pretax traditional IRA withdrawals would generally be included in ordinary income.
Count the traditional IRA’s current tax savings. Spending that savings can leave the Roth with more after-tax retirement value. Investing the savings can make the two results closer when tax rates are equal.
The example leaves out state tax, returns, fees, credits, and future law. It shows tax timing, not a promise.
When a Roth IRA may fit better
A Roth IRA may deserve stronger consideration when:
- You are early in your career or currently in a relatively low tax bracket.
- You expect your taxable income or marginal rate to be higher in retirement.
- You value qualified tax-free withdrawals and do not need a current deduction.
- You want to avoid required minimum distributions from your own Roth IRA during your lifetime.
- You are eligible to contribute directly under the Roth income rules.
- You want some retirement assets that may not increase federal taxable income when withdrawn in a qualified distribution.
A Roth is not best for every young saver. High current income, a valuable deduction, or a lower expected retirement tax rate can favor a different choice.
When a traditional IRA may fit better
A traditional IRA may deserve stronger consideration when:
- You qualify for a full or partial deduction.
- The deduction would reduce income taxed at a relatively high current marginal rate.
- You expect withdrawals to be taxed at a lower rate in retirement.
- Current cash flow makes the near-term tax benefit especially useful.
- You are not eligible for a direct Roth contribution and have carefully evaluated the tax treatment of available alternatives.
A nondeductible traditional contribution gives no tax break now. Learn the recordkeeping and pro-rata rules before using one, especially if you may later convert it to Roth.
Can you contribute to both?
Yes. You can divide an eligible annual contribution between Roth and traditional IRAs as long as the combined amount does not exceed your limit and you satisfy the Roth income rules.
Using both accounts can spread tax risk. Some retirement withdrawals may be taxable, while qualified Roth withdrawals may be tax-free. This mix can help when income or tax rates change.
A workplace 401(k) or 403(b) has a separate limit from an IRA. You may use both. Workplace coverage can still limit a traditional IRA deduction.
Check any employer match before funding an IRA. Contributing too little to earn the full match can mean leaving compensation unused.
An IRA is an account, not an investment
Opening an IRA does not invest the cash. The IRA is an account that holds investments.
After funding the IRA, choose its investments. Options may include mutual funds, exchange-traded funds, and bonds. Cash left in a low-yield settlement fund may not support a long-term goal.
Beginners should compare:
- Account and trading fees
- Expense ratios on funds
- Investment selection
- Minimum investments
- Automatic contribution features
- Customer service and educational support
- Whether the provider is appropriately registered and the account is held by a legitimate custodian
Returns are not guaranteed. Diversification can reduce concentration risk, but market losses remain possible.
A simple five-step decision process
1. Protect your financial base
Keep a workable budget and enough emergency savings before committing every spare dollar to retirement. Early withdrawals can trigger tax, penalties, and lost future growth.
2. Check your workplace plan first
Find out whether your employer offers a 401(k), 403(b), or similar plan and whether it matches contributions. Review vesting rules, fees, and investment choices.
3. Confirm IRA eligibility
Estimate your eligible compensation and modified adjusted gross income. Then check whether you can contribute to a Roth IRA and deduct a traditional IRA contribution.
4. Compare tax value now and later
Compare a deduction now with tax-free qualified withdrawals later. Use your marginal tax rate, not total income alone.
5. Automate and invest deliberately
Choose the account and a diversified investment mix. Name beneficiaries and automate an affordable monthly contribution. Review the plan when your income, work, family, or tax rules change.
Common IRA mistakes
Treating the annual limit as per account
The IRA contribution limit is shared across your Roth and traditional IRAs. Multiple accounts do not multiply the limit.
Assuming every traditional contribution is deductible
Income, filing status, and workplace-plan coverage can limit the deduction even when the contribution is allowed.
Contributing directly to a Roth without checking income
Excess contributions can face a yearly tax until corrected. Recheck the limit when income varies or nears a phase-out.
Forgetting to invest the contribution
Funding an IRA and choosing investments are separate steps. Confirm that your cash was invested as planned.
Withdrawing Roth earnings as if every Roth withdrawal were tax-free
Contributions, conversions, and earnings follow different tax rules. Withdrawal order and qualification matter.
Ignoring Form 8606
Track the basis from nondeductible traditional IRA contributions. Missing records can cause extra tax or reporting work.
Choosing only for the current tax refund
A deduction now can help, but it is only one factor. Also consider future taxable withdrawals, required distributions, and whether you will invest the tax savings.
Frequently asked questions
Is a Roth IRA better than a traditional IRA?
No. A Roth may fit when today’s tax rate is low or tax-free retirement income matters most. A deductible traditional IRA may fit when today’s rate is high and you expect a lower one later.
Can I contribute to an IRA if I have a 401(k)?
Yes, if you have eligible compensation and meet the rules. Workplace coverage can limit the traditional deduction. Income can limit a direct Roth contribution.
Can I contribute to both a Roth and traditional IRA in 2026?
Yes. Your total 2026 contribution is generally limited to $7,500, or $8,600 at age 50 or older. A lower compensation amount also lowers the limit.
Do Roth IRA contributions reduce taxable income?
No. Roth contributions are not deductible. Their main federal benefit is tax-free qualified withdrawals.
Are traditional IRA withdrawals always taxable?
Withdrawals of deductible contributions and earnings are generally taxable as ordinary income. Properly tracked nondeductible basis can make part of a distribution nontaxable.
Can I withdraw Roth IRA contributions before retirement?
IRS ordering rules generally treat regular contributions as coming out before conversions and earnings. Returned regular contributions are generally not included in gross income. Conversions and earnings have separate tax, penalty, and five-year rules. Any withdrawal also leaves less money invested.
Do Roth IRAs have required minimum distributions?
The original Roth IRA owner has no lifetime required minimum distributions. Different rules can apply to beneficiaries.
What if my income is too high for a Roth IRA?
A direct Roth contribution may be reduced or barred. Avoid an excess contribution. Before a conversion, review your other IRAs and the pro-rata tax rule with a tax professional.
The bottom line
Roth contributions use money already taxed and can support tax-free qualified withdrawals. A traditional IRA may offer a deduction now, followed by taxable withdrawals.
Start with eligibility. Check the 2026 limits and whether a traditional deduction is available. Then compare a tax benefit now with tax-free qualified withdrawals later. If the future is uncertain, using both tax treatments over your career can add flexibility.
Continue learning
Turn this guide into a learning path.
Use the matching Finlitera lessons to reinforce IRA tax treatment, retirement planning, and account selection.
Official sources
Sources reviewed September 5, 2026:
- IRS: 401(k) limit increases to $24,500 for 2026; IRA limit increases to $7,500
- IRS: Traditional and Roth IRAs
- IRS Publication 590-A: Contributions to Individual Retirement Arrangements
- IRS Publication 590-B: Distributions from Individual Retirement Arrangements
- Investor.gov: Individual Retirement Accounts
- Investor.gov: First Job retirement toolkit
Finlitera provides general education, not personal investment, tax, or legal advice. Rules and circumstances vary. Check current IRS guidance and seek qualified help when needed.